Long Island City Condos in 2026: What New Units Actually Sell For, and the Real Monthly Cost of Owning One
For buyers looking at condos for sale in Queens, the list price is only part of the picture. New-development closings can show what buyers have actually paid, while common charges, property taxes and mortgage payments shape what ownership costs month to month. Here’s a practical look at recent Long Island City condo sales, the extra costs to budget for, and what the shrinking supply of new homes could mean for buyers and sellers. What new LIC condos actually sold for Over the three years from August 31, 2023, through August 31, 2026, 322 new condos closed in 21 Long Island City buildings. The median closing price was $951,032, or $1,458 per square foot. Prices varied by apartment size: Home type Share of sales Median closing price Median price per sq. ft. Studio 10% $702,593 About $1,666 One-bedroom 51% $908,122 About $1,485 Two-bedroom 36% $1,229,171 About $1,358 Three bedrooms or more 3% $1,775,000 – One-bedrooms made up more than half of the closings. That means buyers searching for this popular layout may have more competition than buyers looking for a less common size. Two-bedrooms had a higher median price, but a lower median price per square foot than studios or one-bedrooms. These are recorded sponsor closings, the first recorded deed for a new home, not current asking prices or resale sales. For current listings and specific units, check the offering details and available Queens apartments for sale with a real estate professional. Prices per square foot have climbed The median price per square foot for new LIC condo closings rose from $1,400 in 2024 to $1,503 in 2025 and $1,617 in 2026. The 2026 figure is based on about 66 closings through August 31, so it reflects a partial year. The median closing price for those 2026 sales was $997,000. Prices are just one comparison point. A unit’s floor, layout, finishes, outdoor space, building finances and tax situation can all affect its value. Buyers should compare similar homes and review the full offering plan, not rely on a neighborhood-wide average alone. The median building’s first sales closed 1% above the sponsor’s list price, and 61% of buildings closed above list. Buildings that began closings in 2023 or later typically sold out in about three months; 48% sold out within a year. Across the broader group of buildings that sold out, the typical time was seven months. The monthly cost is more than the mortgage A realistic ownership budget should include: Mortgage principal and interest, if financing Property taxes Condo common charges Homeowners insurance Utilities and any building-specific costs The median monthly common charge in the reviewed new LIC condo plans was about $571 per home. For comparison, the reported medians were $475 in Astoria and $603 in Greenpoint. Insurance, at about $110 per month per home, and repairs and service contracts, at about $100, were the largest listed pieces of the LIC common-charge budget. That $571 is a median based on building budgets; the charge for a particular apartment can be higher or lower. Ask for the unit’s current charges and review the building’s budget and reserve information. Property taxes are a separate expense and can make a major difference to the total monthly cost. The 421-a tax break ended in June 2022, so buyers in new buildings without an applicable tax benefit may face full property taxes from the start. Don’t assume a tax estimate in a listing will stay the same indefinitely: confirm the details for the specific unit and building. A helpful comparison is to add the expected monthly mortgage payment, property taxes and common charges first, then include insurance and utilities. If you’re comparing ownership with apartments for rent in Queens, compare the total monthly outlay, not just the rent or purchase price. Supply is tighter, but new plans are in the pipeline Since 2023, accepted condo plans have averaged about 331 new homes a year in LIC, compared with 563 a year in 2015–2019-roughly 41% fewer. At the same time, the median asking price per square foot in new plans increased from $1,264 in 2015–2019 to $1,392 since 2023. A smaller pipeline may support values, but it doesn’t guarantee future price increases. And fewer new units do not necessarily mean every existing condo is equally desirable or easy to sell. There are also plans to watch: 16 new condo plans with 1,273 homes were filed since 2025; 10 had been accepted and six were under review in the reported data. A filed plan is not the same as homes available to buy today. Plans under review still need approval before sponsors can sign contracts. A quick checklist for buyers and sellers If you’re buying: Compare recent closing prices by size and price per square foot, then verify taxes and common charges for the actual unit. Review the offering plan for building costs, included amenities, tax information and any other obligations. Amenities can add value, but they can also affect operating costs: 72% of plans since 2015 included shared amenities, while 32% listed a doorman. If you’re selling: Use comparable sales that match your home’s size, condition and building type. New-development closings provide useful context, but they are not a direct substitute for recent sales of similar resale units. LIC also has a strong transit connection: 92% of recent buildings in the data were within a five-minute walk of a subway entrance, with a median walk of three minutes. That convenience, alongside the home itself and its ownership costs, can be part of a buyer’s comparison. Data note: Figures come from public records through August 2026, as reported by The Condo Book, updated October 13, 2026. Closing data covers sponsor sales of new condos and excludes resales. Common-charge and building-feature figures are based on offering-plan information and may not match a specific unit’s current costs. Review the latest offering plan and building documents before making a decision. For help comparing a specific home or understanding local market conditions, connect with Armas Group NYC, a Queens real
Long Island October 2026: Why More Listings Aren’t Easing the Housing Crunch
August 2026 figures point to a market where more homes came up for sale, but the supply available to buyers still did not grow. The numbers below are for single-family homes and were current as of September 8. More homes listed, fewer homes available At first glance, August looked like it might bring some relief for Long Island buyers. Nassau County recorded 951 new single-family listings, up 6.0% from a year earlier. Suffolk had 1,305, up 2.9%. But new listings measure homes entering the market during a period. Inventory measures the homes still available at a particular point in time. By the end of August, Nassau had 2,259 single-family homes for sale, down 0.4% year over year. Suffolk had 3,129, down 3.9%. Together, the counties had 91 more new listings than in August 2025, but 135 fewer homes in inventory. That contrast suggests the additional supply wasn’t enough to build a larger pool of available homes. Some listings may have sold quickly; others may have been withdrawn or otherwise left the active market. The figures don’t track every listing’s path, but they do show that inventory remained tight. Prices and competition remain strong Closed sales edged lower: Nassau recorded 881, down 3.0% year over year, while Suffolk recorded 1,119, down 0.9%. Yet the median single-family sale price rose to $911,000 in Nassau, up 4.7%, and $760,000 in Suffolk, up 7.0%. Homes also continued to sell near or above their original asking price. Nassau sellers received 100.5% of original list price on the typical closed sale; in Suffolk, the figure was 102.2%. These are market-level measures, not a promise that every home will sell above asking. They do show that competition remained meaningful in many parts of the market. Homes spent about 38 days on the market in Nassau and 39 in Suffolk. Those countywide averages offer useful context, but an individual home’s timing and buyer interest depend on its location, condition, price, and competition. Not every kind of home followed the same pattern Single-family homes don’t tell the whole story. In August, Nassau’s condo median fell 10.8% to $740,000, and the co-op median declined 5.0% to $380,000. Those changes came from relatively small monthly samples-74 condo sales and 71 co-op sales, so they should be treated cautiously. In Suffolk, the condo median rose 4.7% to $570,000, while condo inventory dropped 24.8%. If you’re buying or selling a condo or co-op, single-family statistics may not reflect the conditions you’ll encounter. What buyers can do More listings don’t automatically mean more negotiating room. If you’re shopping, focus on homes that fit your needs and budget rather than assuming the countywide numbers apply to every neighborhood. Get financing and paperwork ready. In a competitive situation, a clear pre-approval and prompt response can help you move with confidence. Compare relevant homes. Recent sales nearby, property condition, and active competition are more useful for setting an offer than a county median alone. Set a firm comfort zone. A sale-to-list ratio above 100% doesn’t mean you should exceed your budget. Decide what works for you before making an offer. Look across property types and areas. Condos, co-ops, and single-family homes can move differently, as can neighboring communities. What sellers can do The numbers suggest sellers of well-positioned single-family homes may still find serious buyers, but they don’t make pricing or preparation less important. Price for the local market. A county median can’t account for a home’s specific location, condition, layout, or recent nearby sales. Prepare the home before listing. Addressing visible maintenance issues and presenting the home clearly can help buyers assess its value. Review the plan with an experienced local professional. Pricing, marketing, showings, and offer terms all shape the outcome, not just the number of listings entering the market. For a local assessment, contact Armas Group NYC to discuss buying, selling, or a complimentary home value estimate. Data note: The figures in this article are August 2026 OneKey MLS county statistics for single-family homes, current as of September 8. Countywide results can differ sharply by community. See the Nassau County report, Suffolk County report, and OneKey MLS market statistics.
NYC Real Estate October 2026: Signs of Stabilization Despite Elevated Mortgage Rates
Manhattan’s September market was quieter than a year ago, but early October brought a few signs that activity may be finding its footing. Buyers and sellers should take note, but it is too soon to call this a confirmed turnaround. Reported figures vary by source and reporting window, so monthly totals and weekly updates may not line up exactly. Here’s what the latest numbers suggest as of mid-October. A busier week, after a slower September Manhattan recorded 588 signed contracts in September, down 20.1% year over year, according to a monthly market report from Brown Harris Stevens. That points to a selective market, not one where every home is drawing strong demand. The weekly picture was more encouraging. For the week ending October 11, Manhattan recorded 195 signed contracts. The highest weekly total since late July, according to Howard Hanna NYC’s weekly update. One strong week does not establish a lasting trend, but it suggests buyers were still making moves despite higher borrowing costs. Inventory is rising, but the pace matters Manhattan inventory ended September at 5,986 properties and reached about 6,101 by mid-October in weekly reporting. More available homes can give buyers additional choice and negotiating room. At the same time, the pace of new supply and the number of homes going under contract help show whether that inventory is building faster than demand can absorb it. The mid-October contract figure is a useful signal, but not proof that supply has peaked or that prices are about to rise. Buyers and sellers should look at current conditions in the specific neighborhood and property type they care about. Luxury activity stands out The market is not moving at the same speed in every price range. Homes priced at $4 million and above recorded 77 signed contracts in September, outperforming the broader Manhattan market, according to Brown Harris Stevens’ report. That strength at the luxury end does not mean all high-priced homes are selling quickly, or that other segments are recovering. Property condition, pricing, location and buyer demand can make a major difference at every price point. Mortgage rates remain a major consideration Mortgage rates were recently reported around 7.5%–7.6%. At those levels, even a modest change in a buyer’s rate can affect monthly payments and purchasing power. Buyers may be active, but financing costs can still narrow their options. What buyers can do now Get a current financing estimate. Ask a lender to calculate payments using a realistic rate, taxes, common charges and other costs. Compare carefully. More inventory can create opportunities, but compare similar homes and check recent sales before making an offer. Be ready, not rushed. A busier week does not mean every listing will attract competition. Focus on the property’s value and your budget. Get guidance on the property type. Co-ops, condos and multifamily homes can involve different costs and purchase steps. What sellers can do now Price for today’s buyers. With borrowing costs elevated, buyers may be especially sensitive to price and monthly expenses. Prepare the home thoughtfully. Strong presentation, clear listing details and good-quality photos can help buyers assess a property. Pay attention to comparable sales and active competition. A broad market statistic is not a substitute for a local pricing review. Plan for negotiation. Be clear about your priorities and consider offers based on their full terms, not just the headline price. A cautious signal, not a confirmed reversal September’s lower contract count and the early-October weekly increase tell two parts of the story: demand was subdued over the month, but activity picked up in one reported week. Luxury contracts also held up better than the wider market. Meanwhile, rates near 7.5%–7.6% remain a meaningful hurdle for many buyers. For now, the practical approach is to make decisions based on your finances and the specific property, not a prediction that the market has turned. Armas Group NYC helps buyers, sellers and property owners navigate Queens and the wider NYC area. For local guidance or a free property value assessment, connect with Armas Group NYC.
Long Island City Real Estate October 2026: How Buyers Can Use Longer Listing Times to Negotiate
For Long Island City buyers, a home that has been listed for weeks, or has already had a price reduction, may offer room for a thoughtful negotiation. But extra time on the market does not automatically mean a seller will accept a low offer. The key is to understand what the listing history and comparable sales actually say about that particular property. What the October market figures suggest Recent Long Island City reports show a market where some listings are taking longer to sell and some sellers are adjusting their asking prices. Depending on the source and reporting window, snapshots point to approximately 138 active listings, a median asking price near $1.09 million, and median time on market in a range of roughly 55 to 86 days. Reported median close prices are approximately $1.04 million to $1.07 million, while about 23% to 25% of listings have had price reductions. These are reported ranges, not a prediction for every apartment or home. Sources may cover different neighborhoods, property types, listing feeds, and time periods. For example, Milton Coste’s Long Island City market update and Realtor.com’s Long Island City market page do not necessarily count the same properties or measure the same window. A broader inventory count should not be compared directly with a narrower neighborhood snapshot. Also, median asking price and median closed price describe different groups of properties. Their difference does not mean every seller will discount by that amount. Building, unit condition, views, monthly costs, and recent comparable sales all matter. How buyers can turn listing time into useful information A longer listing period can be a reason to investigate, not a reason to assume the seller is desperate. Before making an offer, look into: Comparable closed sales: Focus on homes with similar size, condition, building type, and location. Recent closed prices are more useful than a seller’s asking price alone. Price history: Check whether the home has had a reduction, been relisted, or spent time on the market under a previous listing. Competition: Compare it with similar active listings. If buyers have several close alternatives, the seller may have more reason to negotiate. Building and ownership costs: Review common charges or maintenance, taxes, assessments, building financials, and any upcoming work. These costs affect what the home is worth to you. Condition and terms: Note needed repairs, dated finishes, and any timing or occupancy needs that could affect the seller’s decision. As a practical guide, a listing that has been active around or beyond the local reported range of 55–86 days is worth a closer look. It is not proof of a problem or a guarantee of a bargain. A well-priced, move-in-ready home may still attract strong interest, while a home with a high asking price or substantial monthly costs may be harder to sell. Make a persuasive offer, not just a lower one Build your offer around evidence. If comparable sales support a lower value, explain the reasoning clearly. Include relevant repair estimates or building-cost information when appropriate, and be ready to show mortgage preapproval or proof of funds. Consider the full offer, not just the purchase price. Depending on the property and the seller’s priorities, you might negotiate for repairs, a closing credit where permitted, a flexible closing date, or included fixtures. Keep your financing, inspection, and other appropriate protections in place, and review co-op or condo requirements with your agent and attorney. A seller may value a reliable buyer and a clear path to closing as much as a higher headline number. Your offer should be competitive enough to be taken seriously while still reflecting your budget and the property’s value. Sellers: respond to the market before a listing goes stale For sellers, longer listing times and price reductions elsewhere are a reminder to check that your asking price matches the current competition. Start with recent sales of similar homes in the same building or a genuinely comparable one. A broad neighborhood median can hide important differences between a co-op, condo, new development, and resale unit. Strong preparation can help buyers see value from the first showing. Declutter, handle straightforward repairs, use clear photography, and make monthly costs and building information easy to understand. If activity is weak, review the feedback and competing listings promptly. A meaningful price adjustment may attract more attention than several small reductions, but the right move depends on your goals, timing, and property. Longer market time can create an opportunity for prepared buyers, and a signal for sellers to reassess. Neither side should rely on a single headline number. Use the specific property’s condition, comparable sales, carrying costs, and offer terms to guide the decision. For local guidance on buying or selling in Queens and the surrounding NYC area, contact Armas Group NYC.
Long Island in October 2026: Record Prices, Thin Inventory, and What It Means for Buyers and Sellers
Long Island home prices reached a new high in the third quarter of 2026, even as the number of homes for sale remained well below typical levels. For buyers, that means fewer options and a need to be ready when the right home appears. For sellers, limited competition can support strong pricing, but preparation and a realistic asking price still matter. The latest numbers: record prices, limited choice The median home price on mainland Long Island reached $782,000 in Q3 2026, a record and an increase of 4.3% from a year earlier, according to Q3 market data. Total listings stood at about 5,053, roughly 35.8% below the decade average. August single-family figures show how prices differ by county. Nassau’s median closed sale price was $911,000, up about 4.7% year over year. Suffolk’s was $760,000, up about 7.0%. August inventory was approximately 2,259 homes in Nassau and 3,129 in Suffolk, according to this Long Island market report. These numbers cover different time periods and measures: the 5,053 figure is Q3 regional listing inventory; the county inventory counts are for August and single-family homes. They should not be treated as one combined snapshot. Why prices keep climbing The main pressure is limited supply. When too few homes are available, buyers compete for the properties that fit their needs. That can help sustain prices even when sales activity is slower than a year earlier. Low inventory does not mean every home will sell quickly or at any price. Condition, location, property type, and asking price still shape the result. But with listings far below the long-term average, well-prepared homes can attract serious attention. What buyers can do now In a thin-supply market, preparation makes it easier to act confidently: Get pre-approved before touring. Know your budget and have financing documents ready. Compare the full monthly cost. Include mortgage, taxes, insurance, maintenance, and commuting expenses, not only the asking price. Check the actual property-tax bill. Taxes vary by school district, town, village, and special district. Nassau buyers can look up parcel information through the county’s Land Records Viewer. Suffolk buyers can review the county’s property-tax FAQs and contact the relevant town for current bills. Test the commute you would actually make. Check the station, parking, transfers, and peak-hour service using the MTA LIRR timetables. Nassau and Suffolk each offer different location and commute trade-offs. What sellers should keep in mind Thin inventory can give sellers an advantage, but buyers still compare value. Before listing, take care of visible repairs, declutter, and present the home clearly in photos and showings. A local pricing review should account for recent nearby sales, the home’s condition, and current competition, not just record-setting headlines. The listing calendar can matter, too. Spring often brings more choice and activity; fall can still reach motivated buyers, though the pool of listings may be smaller. The best time to sell depends on your property, plans, and local competition. Pricing and preparation matter in either season. A practical next step For buyers, the key is to prepare without rushing into a home that does not fit your budget or priorities. For sellers, it is to understand the value of your particular property and make a plan before going to market. A neighborhood-level assessment can help clarify the options. If your plans also involve Queens (perhaps you’re comparing homes for sale in Queens NYC or searching “sell house fast Queens NY”) our Queens real estate agency can help with that part of your move, too.
NYC Real Estate Market in October 2026: Borough-by-Borough Snapshot
New York City’s housing market remains competitive, but conditions vary by borough and property type. The latest reported citywide median sale price is about $923,000. At the same time, limited inventory and mortgage rates above 7% are making it important for buyers and sellers to plan carefully. The borough figures below come from reports covering different periods and property types, so they are useful as a snapshot, not a direct, like-for-like ranking. A recent 30-day NYC market report and Q3 reporting help show the range of current prices. Manhattan: High prices, limited choice Manhattan’s median sale price is roughly $1.25 million to $1.275 million. The Q3 Corcoran report counted about 6,354 active listings. That may sound like a large selection, but buyers still face strong competition for well-priced homes in desirable locations. For buyers, preparation matters: have financing lined up and be ready to act when a suitable property appears. Sellers should price against recent comparable sales, not just the highest asking prices. A realistic price and thoughtful presentation can help a listing stand out. Brooklyn: Prices depend on the neighborhood and home Brooklyn’s reported median ranges from about $1.16 million to $1.29 million, depending on the reporting period and property mix. Recent market updates show that inventory has been changing, but more listings do not automatically mean buyers will find an affordable or suitable home. Buyers should compare similar properties within the same neighborhood and account for monthly costs, including common charges, taxes and mortgage payments. Sellers can benefit from renewed buyer interest when their home is prepared well and priced in line with local competition. Queens: More price variety, but inventory is still tight Queens remains an important option for buyers seeking a wider mix of homes and price points. Recent median estimates range from about $725,000 to $775,000. The lower end of that range reflects a recent short-term market snapshot; Q3 figures can differ because of timing and the types of properties counted. The real estate market in Queens, NY varies greatly from one neighborhood and property type to another. Buyers looking at homes for sale in Queens, NYC, or Queens apartments for sale, should compare similar homes nearby and consider commute, condition and monthly expenses, not just the asking price. For sellers, limited inventory can help a well-presented property attract attention, but it does not guarantee multiple offers. Accurate pricing, strong photos and a clear plan for showings matter. A local Queens real estate agency can help evaluate recent comparable sales and position a listing for the right buyers. The Bronx and Staten Island: Read the numbers with care The latest short-term report put the Bronx median near $425,000, based on a relatively small number of sales. Staten Island did not have enough sales in that report to provide a reliable median. These figures can move noticeably from one reporting period to another, so buyers and sellers should seek neighborhood-level comparisons rather than rely on a borough-wide number alone. What low inventory and higher rates mean Mortgage costs are a major part of today’s affordability picture. Freddie Mac’s mortgage-rate archive reported a national 30-year fixed average of 7.28% on October 1, 2026. Jumbo APRs were around 7.44% at that time. These are benchmarks, not personal offers; actual rates depend on the borrower, loan, property and lender. For buyers, even a small rate change can affect a monthly payment. Get pre-approved before making offers, ask a lender to explain the full monthly cost, and set a budget that leaves room for taxes, insurance and building charges. Compare options with your lender rather than assuming rates will fall soon. For sellers, low inventory may bring serious buyers to a well-prepared listing, and multiple offers are still possible. But buyers are payment-conscious. Pricing too high can cause a home to sit while better-positioned listings attract attention. Landlords should also review current rental competition and prepare a clear, complete application process to connect with qualified tenants. Practical next steps this month Buyers: Get pre-approved, understand your maximum monthly payment and be prepared to move quickly on a good fit. Sellers: Review recent comparable sales, prepare the home for photos and showings, and price realistically from the start. Renters: Gather application documents early and compare the full cost and terms of each rental. Landlords: Present the property clearly, set competitive terms and respond promptly to qualified applicants. The October market rewards preparation. For a Queens home value assessment, help finding a property, or guidance on a sale or rental, contact Armas Group NYC.
Long Island City Condos in October 2026: Prices, Inventory and What Buyers Should Expect
Long Island City remains a high-priced condo market, but the latest numbers tell a more nuanced story than “every home is getting snapped up.” Buyers have limited options to choose from, yet some listings are reducing prices and giving buyers room to negotiate. LIC market snapshot A Long Island City market report puts the recent median sale price at about $1.1 million. Its October 2 report gives a six-month median of about $1.05 million, up 8.2% year over year. A separate October 12 snapshot shows 137 active listings, with condos making up about 93% of available homes. The broader October estimate is roughly 137–138 listings, with condos representing about 93–94% of inventory. Homes spent a median of about 55 days on the market, and sales closed at close to 100% of original asking price. These are rolling-period and point-in-time figures, not final totals for the full month. Median prices can also vary with the time period and mix of homes sold. That small number of listings is one reason buyers may feel the choices are limited. Condos dominate the options, while co-ops and other property types make up a small share. Still, limited inventory does not mean every listing is drawing a bidding war: the October 12 snapshot showed price reductions on about a quarter of active homes. In today’s real estate market Queens NY, each property’s pricing, condition and time on market matter. What buyers should budget beyond the price When comparing condos for sale in Queens, look past the asking price to the full monthly cost and the cash needed at closing. Common charges: These cover your share of building expenses. Ask what they include and whether the building has planned work or assessments that could affect costs. Property taxes: Condo owners generally receive a separate property-tax bill. Check the unit’s current bill and whether it receives a tax abatement. The NYC Department of Finance explains eligibility and savings; benefits depend on both the building and owner. Closing costs: Buyers may need to budget for legal, title, lender and building fees, along with applicable taxes. For eligible residential purchases of $1 million or more, New York’s mansion tax starts at 1% of the purchase price. A financed condo may also incur mortgage recording tax. The NYC Department of Finance recommends using ACRIS to calculate the amount due. For a purchase near LIC’s median, these costs can add up to a significant sum. Ask your attorney and lender for an itemized estimate before making an offer. Review the building’s budget, recent financials, any planned assessments, and whether a tax benefit could change. How to compete without overpaying Get mortgage pre-approval and decide your maximum budget before touring. Include estimated taxes, common charges, utilities and closing costs in that number. This will help you compare Queens apartments for sale based on what you can comfortably afford, not just the list price. When you find a promising home, compare it with recent sales in the same building or nearby buildings. Ask whether the asking price reflects the unit’s condition, floor, views and building costs. A well-priced home may still attract serious interest, but a listing with a price reduction or longer market time may allow more room to negotiate. Move promptly when the numbers make sense, but do not skip a careful review of the building and apartment. What LIC sellers should know A median sale price is a neighborhood guide, not a recommended asking price for every home. Buyers are comparing similar units and weighing ongoing costs, so an ambitious price can make a condo harder to stand out, especially when nearby listings offer more value. Before setting a price, review recent comparable sales, current competition and the details that make your unit different. Strong presentation and clear information about common charges, taxes and building finances can help buyers assess value. With median time on market around 55 days, a realistic launch price can help attract attention early, while the near-100% sale-to-original-ask figure suggests that successful pricing remains important. Whether you are buying or selling, local guidance can help you weigh the numbers and plan your next step. Contact Armas Group NYC to discuss the LIC market and your real estate goals.
Long Island Real Estate in 2026: What Buyers, Sellers and Renters Need to Know
Market update: October 12, 2026. The latest county figures cited below are for September and focus on single-family homes. Prices and conditions vary by town, property type and price range. Long Island’s Nassau and Suffolk housing markets remain competitive, but conditions are not the same everywhere. September data show home prices rising year over year, a modest increase in homes for sale and continued competition for many well-priced listings. Mortgage rates are also weighing on what buyers can afford. For people moving from Queens or elsewhere in New York City, Long Island can offer more space and different housing choices, but the right fit depends on more than the asking price. Commute, property taxes, maintenance and neighborhood conditions all matter. September market snapshot: Nassau and Suffolk In September 2026, the median single-family sale price was $858,000 in Nassau County, up 2.1% from a year earlier, and $740,000 in Suffolk County, up 2.8%. Homes for sale were up about 4.5% in Nassau and 4.3% in Suffolk year over year. Even so, supply remained limited at roughly 3.3 and 3.4 months, respectively, according to September county market reports and Suffolk County market data. A separate analysis of September sales found about 56% of homes sold above their final asking price, while roughly 34% sold below. Competition was especially common in the $600,000–$1 million range. These figures use different measures from the county reports’ sale-to-original-list-price statistics, so they should not be treated as interchangeable. See the analysis of where Long Island buyers are still competing. A county median is a guide, not a price estimate for a particular home. The mix of properties that sell changes from month to month, and local results can differ considerably. Mortgage rates are part of the budget On October 8, Freddie Mac’s national weekly average for a 30-year fixed mortgage was 7.40%, up from 7.28% the previous week. This is a national average, not a rate quote; a borrower’s rate depends on their finances, loan type and other factors. Check the latest Freddie Mac mortgage rate data, and compare lender offers. At today’s rates, even a small change in the loan amount or down payment can make a meaningful difference to monthly costs. Buyers should get pre-approved, set a comfortable payment limit and budget for taxes, insurance, utilities and maintenance, not just principal and interest. North Shore, South Shore and central Long Island North Shore: Many communities are known for wooded streets, varied architecture and proximity to the coastline. Some areas command higher prices, but the North Shore is not one uniform market. Compare individual towns and properties, and check commute options, taxes and any waterfront-related insurance or maintenance needs. South Shore: The housing mix ranges from inland neighborhoods to bayside and coastal areas. Water access can be a draw, but buyers should carefully investigate flood exposure, insurance availability and potential maintenance costs. A home’s distance from the water, and its specific elevation and location, can matter. Central Long Island: Communities farther from the coast may appeal to buyers looking for a different balance of price, space and access to jobs or rail service. But “central” does not automatically mean affordable. School district, property condition, transit access and local demand can all affect prices. For renters and buyers commuting to the city, check the actual door-to-door trip at the times you expect to travel. A station nearby on a map may not make the commute simple if parking, transfers or peak-hour schedules do not work for you. What buyers should do to compete Start with a firm budget and a mortgage pre-approval. Then compare a home with recent sales in the same area and similar property type. In a competitive price range, a well-prepared buyer may need to act quickly, but an offer above asking should be based on comparable sales, not pressure or the listing price alone. Before committing, review the property’s condition, taxes, insurance needs, possible repairs and any relevant town or county requirements. Buyers moving from Queens, including Flushing, Bayside, Whitestone and Bellerose, should also compare the full cost of ownership with their current housing costs. More space can come with different expenses and a longer commute. What sellers should know about pricing Low inventory can support sellers, but it does not guarantee that every home will sell quickly or above asking. Price, condition, presentation and competition all influence the result. The September figures show why it is useful to look at your town and price range rather than rely on a broad Long Island headline. Before listing, review comparable recent sales and active competition. Take care of visible maintenance issues, prepare the home for showings and consider the likely buyer for your property. A realistic asking price can help attract serious interest; an inflated price may cost valuable time and lead to later reductions. Renters: compare the full cost and the daily routine Long Island rentals vary by community, building type and proximity to rail, schools and shopping. When comparing homes, ask what is included in rent, who pays utilities, whether parking or other services cost extra, and what the lease says about renewals and maintenance. Consider the commute, too. Check the train schedule, parking arrangements and travel time from the specific address, not just the town. If you are relocating from Queens or the city, renting first may give you time to learn the area before deciding where to buy. Plan your next move with local guidance Long Island’s late-2026 market offers opportunities, but buyers, sellers and renters need to evaluate the details at the town and property level. Armas Group NYC helps clients navigate residential real estate across Queens and the surrounding New York area with clear communication and personalized guidance. Learn more or reach out through Armas Group NYC. Market figures are snapshots, not guarantees or property valuations. Mortgage rates are national averages and can change. Confirm current market conditions and property details before making a decision.
Renting in Long Island City: What It Really Costs in 2026, And How to Win the Apartment
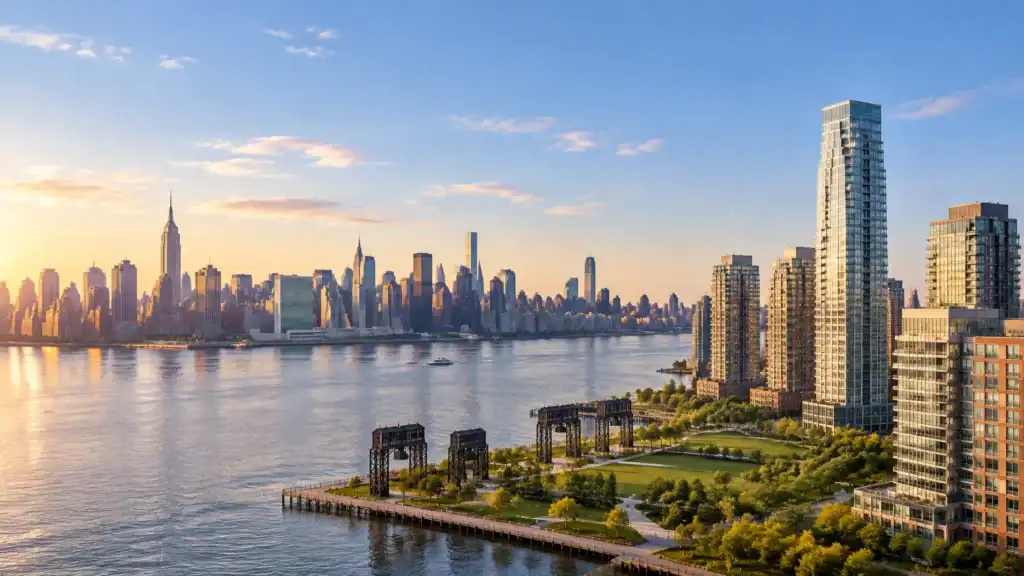
Long Island City remains one of New York City’s most desirable rental destinations in 2026. Modern residential buildings, waterfront parks, restaurants, and direct transportation links make it a compelling alternative to Manhattan for renters seeking convenience, space, and amenities. But renting in LIC takes more than finding an attractive listing. You need a realistic budget, a complete application, and the ability to move confidently when the right apartment becomes available. This guide covers rental costs, expenses beyond advertised rent, differences between LIC neighborhoods, and ways to strengthen your application. Market note: The figures below are directional 2026 asking-rent ranges, not guarantees. Actual pricing varies by building, floor, views, amenities, lease term, concessions, condition, and availability. What Renters Are Paying in Long Island City in 2026 Market data from sources including Apartments.com, Zumper, RentCafe, and Apartment List puts LIC’s overall rental market generally in the mid-$4,000s per month across unit types. Treat that as a broad planning reference; base your budget on the apartment type, building, and move-in timing you want. Luxury towers, waterfront residences, and apartments with expansive skyline views can cost more. Older buildings and apartments farther from the waterfront may have different pricing, especially when they offer fewer amenities or services. Concessions can also affect the calculation. One month free on a 12-month lease may lower the effective monthly rent, while gross rent, the security deposit, and income qualification may still be based on the stated lease rent. Compare gross rent, net effective rent, and total move-in costs before deciding. LIC Versus Manhattan: The Commute Adds Real Value LIC is not simply a lower-cost substitute for Manhattan. It offers a different balance of location, space, amenities, and lifestyle. Directional 2026 comparisons place Manhattan studios around the mid-$3,000s and LIC studios around the mid-$3,000s. Manhattan one-bedrooms are around the low-$4,000s, compared with approximately $4,000–$4,200 in LIC. Manhattan two-bedrooms are around the high-$5,000s, while LIC two-bedrooms are approximately $5,600–$5,900. LIC one- and two-bedrooms may be somewhat less expensive than comparable Manhattan inventory, while studio prices can be similar depending on the building sample. LIC offers access to the 7, E, M, G, R, N, and W subway lines, depending on location. Check the MTA subway map before signing: the nearest station can shape your daily routine. NYC Ferry also serves areas near Hunters Point South and Gantry Plaza State Park. Check current routes and schedules to see whether the ferry works for your commute. Three LIC Areas, Three Rental Experiences Hunters Point: Waterfront Lifestyle and Full-Service Buildings Hunters Point is known for waterfront parks, skyline views, Gantry Plaza State Park, and modern residential buildings. Many offer doormen, fitness centers, lounges, roof decks, coworking spaces, and package services. That convenience can come with a premium. Check amenity access, utility billing, pet policies, and parking; some services may cost extra. Hunters Point may suit renters who value views, outdoor space, amenities, and a polished residential setting. Court Square and Queens Plaza: Connectivity and New Development Court Square and Queens Plaza offer strong transit access to the E, M, G, 7, R, N, and W lines, depending on station and direction. Newer apartment buildings and high-rises provide options from compact studios to larger homes. If a direct commute is a priority, compare the apartment’s distance from transit, building management, and complete fee schedule, not just the advertised rent. Vernon Boulevard: Neighborhood Convenience with a More Local Feel Vernon Boulevard offers restaurants, cafés, shops, and an established neighborhood feel. It appeals to renters seeking everyday conveniences near the waterfront and 7 train. Building types vary, from newer residences to smaller buildings with fewer amenities. Compare natural light, noise, laundry, storage, renovation quality, and maintenance, not only price. What Your Lease Covers, and What It May Not Base rent generally covers the right to occupy the apartment and services specifically included in the lease. It does not automatically include every building service. Before signing, request a written breakdown of amenity or recreation fees; pet rent or one-time pet fees; parking and storage; electricity, gas, water, or submeters; internet and cable; move-in or elevator fees; and package, bike, or resident-service fees. In condo-style or amenity-rich buildings, renters may hear terms such as “common charges.” Tenants generally do not pay an owner’s common charges as an owner would, but a lease may pass through specific building costs or require separate payments for optional services. The NYC Department of Consumer and Worker Protection broker-fee FAQ provides guidance on rental fees and broker compensation. What Landlords Look For When Choosing Between Applicants Landlords and management companies commonly evaluate credit and payment history, employment and income stability, bank statements and liquid assets, identification and rental history, debt obligations and public records, guarantor strength, and the ability to meet application deadlines. A common market-rate guideline is annual income of about 40 times the monthly rent. For a $4,200 apartment, that is approximately $168,000 a year. It is a common underwriting practice, not a universal legal requirement. Guarantors are often expected to meet stronger standards, frequently around 80 times monthly rent; requirements vary. Prepare government-issued ID, recent pay stubs or employment verification, tax returns, bank or asset statements, landlord references or prior lease information, guarantor documents if applicable, and a short explanation for any credit or employment issue. Under New York rules, standard rental application fees are limited to the actual cost of a background and credit check, up to $20. A portable screening report may help avoid the fee if it meets current requirements. Confirm the policy for your rental. How to Win the Apartment: A Practical Timeline Before you search: Set a maximum monthly budget including utilities, parking, pet costs, and transportation. Decide whether you need a no-fee apartment, doorman, parking, home office, or specific commute. Before you tour: Organize documents digitally. Confirm income qualification, guarantor options, move-in date, and preferred lease term. At the showing: Ask about gross and net effective rent, required fees, concessions, utilities, pet policy, and application timing. Review the actual apartment, not only a
Buy Now or Wait for Rates to Drop? What Queens Buyers Need to Know in 2026
Queens buyers are weighing higher mortgage rates against limited inventory and rising home prices. If you are a first time home buyer in Queens, today’s mortgage market may feel discouraging. The average 30-year fixed mortgage rate is about 7.42% as of October 6, 2026, and rates have moved back above 7% as inflation concerns and bond-market volatility continue. That naturally raises the question: should you buy now or wait for rates to fall? The best answer is not based on predictions. It is based on whether the numbers work for your budget, your timeline, and the property you want. Queens buyers are facing two competing trends Queens inventory remains tight, with less than three months of supply. Borough-wide home prices are projected to rise approximately 3% to 6% this year. Current market indicators show a median listing price near $650,000, a median sold price around $710,000, approximately 73 days on market, and homes selling for close to 98% of asking price. That means waiting could bring lower rates someday, but it could also mean paying more for the home itself. If prices rise while you wait, the savings from a lower interest rate may be smaller than expected. Armas Group’s Q2 2026 Queens medians also show why property type matters: Co-ops: approximately $385,000 Condos: approximately $545,000 Single-family homes: approximately $712,000 Two-to-four-family homes: approximately $985,000 Your monthly budget should include more than the mortgage payment. How to compare buying now with waiting Start with two honest calculations. First, calculate the cost of waiting. Estimate how much the home you want could cost if Queens prices rise by 3% to 6%. On a $650,000 property, a 3% increase equals $19,500. A 6% increase equals $39,000. Then consider the extra down payment and loan amount that may result from that higher price. Second, calculate the potential rate savings. A lower rate could reduce your monthly principal-and-interest payment. However, the savings depend on your loan amount, credit profile, down payment, and the rate available when you are ready to refinance or buy. A lender can compare both scenarios using your actual numbers. Do not rely only on national headlines or rate forecasts. Buying now does not mean you are stuck at today’s rate If rates fall later, you may be able to refinance. Refinancing replaces your current mortgage with a new loan at a lower rate, potentially reducing your monthly payment. However, refinancing is not automatic or guaranteed. You will need sufficient equity, qualifying income, acceptable credit, and enough savings to cover closing costs. A lower rate may not make sense if the savings take many years to recover those costs. The practical strategy is to buy only when the payment is comfortable today, and view refinancing as a possible future option, not a promise. Ask about rate buydowns A rate buydown may help make a purchase more affordable. With a permanent buydown, the borrower pays discount points at closing to reduce the interest rate for the life of the loan. With a temporary buydown, the rate is reduced for an initial period, often through a 2-1 structure, before returning to the regular note rate. A seller may agree to pay for a buydown as part of the negotiation. Buyers should compare the upfront cost, monthly savings, and long-term benefit with their lender. A seller-paid closing credit could also help cover eligible closing expenses, preserving more of your cash. Focus on what you can control You cannot control the Federal Reserve, inflation, or bond-market movements. You can control several important parts of the purchase: The price you offer and negotiate The size of your down payment Seller-paid closing credits Mortgage points and loan structure Building maintenance charges Property taxes and insurance Your credit score and debt levels The type and location of property you choose For example, a co-op with a lower purchase price may be more affordable than a condo, but you must evaluate the monthly maintenance, building finances, sublet rules, and board requirements. Review the complete monthly cost, not just the advertised price. Queens entry points still exist Buyers searching for homes for sale in Queens NYC may find entry points under $400,000 in areas such as Jamaica, Woodhaven, and St. Albans. Queens co-ops in Jackson Heights, Sunnyside, and Woodside can also offer a lower purchase price than many condos or single-family homes. Buyers looking at condos for sale in Queens should compare common charges, taxes, insurance, assessments, and financing requirements. A lower-priced unit is not automatically the lower-cost choice. First-time buyers should also investigate programs before making an offer. NYC’s HomeFirst Down Payment Assistance Program may provide eligible buyers with assistance for down payment and closing costs. New York’s SONYMA homebuyer programs may also offer fixed-rate financing and down payment assistance, subject to current eligibility rules. Queens buyers should compare neighborhoods, property types, and total monthly costs. What if the numbers do not work yet? Waiting can be the right decision if the payment would stretch your budget or leave you without emergency savings. Use that time productively: Build a larger down payment and closing-cost reserve. Reduce credit-card balances and other monthly debt. Improve your credit profile. Complete an approved first-time buyer education course. Compare co-ops, condos, and smaller homes. Ask a lender which assistance programs may apply. Track realistic properties instead of relying on broad market predictions. The goal is not to guess the perfect month to buy. The goal is to become financially ready and act when a suitable Queens property fits your budget. Get a Queens market evaluation before you decide The Queens real estate market is highly localized. A co-op in Sunnyside, a single-family home in St. Albans, and a multifamily property in Jamaica can have very different pricing, financing, and resale considerations. A knowledgeable Queens real estate agency can help you compare the cost of buying now with the cost of waiting, review available properties, estimate monthly expenses, and negotiate terms that may improve affordability. Armas Group NYC provides local guidance for buyers across Queens